All Categories
Featured
Early Loss Prevention Tactics for Borrowers
Table of Contents
Here are some steps to help you and your family discover out if you have choices to prevent foreclosure. Make or take the call. The rules set standards that need home mortgage servicers to attempt to assist you. Your home loan servicer typically has to try to talk to you about the alternatives to avoid foreclosure.
If you had a fire in your home, you 'd call an expert firemen. The very same opts for a real estate emergency. You can find professional advice you can trust by getting in touch with Kansas Legal Solutions. There is no cost to you. Scammer are attempting to take benefit of homeowners who get into problem by charging them thousands of dollars for incorrect promises of assistance.
If you send a total application early enough, your home loan servicer is required under the brand-new rules to evaluate you for all the alternatives readily available to you that may permit you to keep your home or leave your home if you prefer that option. Loan providers may use programs to decrease monthly payments or lower a customer's interest rate.
If you finish your application for aid, you also are safeguarded from foreclosure while it is evaluated. The U.S.Consumer Financial Protection Bureau (CFPB) accepts problems about mortgages, so if you have a problem, you can send a problem to the CFPB.
Comparing Home Loan Modification Relief Options
Submit a complaint at or by calling (855) 4112372 TTY/TDD (855) 7292372. Look for help from Kansas Legal Services or call our application line if you are being threatened with foreclosure and need recommendations or representation. - Judicial Foreclosure Available: - Non-Judicial Foreclosure Available: - Main Security Instruments: - Timeline: - Right of Redemption: - Shortage Judgments Allowed: In Kansas, lenders might foreclose on a home mortgage in default by utilizing the judicial foreclosure procedure.
Usually, after the court states a foreclosure, the property will be auctioned off to the greatest bidder. The notification of the time and sale must be advertised as soon as a week for 3 (3) successive weeks, with the last publication disappearing than fourteen (14) and no less than seven (7) days before the scheduled date of sale.
The sale is by public auction to the greatest bidder, who will get a certificate of purchase. After the sale is validated, the winning bidder will be entitled to get a constable's deed, which will vest good and perfect title to the foreclosure bidder, when the debtor's right of redemption has ended.
Lenders might sue to obtain a deficiency judgment for the difference in between the foreclosure price and the quantity due on the original home loan. to the Kansas Bar Foundation for their generous support of this program! Last updated on September 03, 2025.
Handling Debt with Strategic PlanningWill Refinancing Help the House in 2026?
The Michigan Foreclosure Prevention Program is a project of the Michigan Poverty Law Program (MPLP), a cooperative effort of Legal Solutions of South Central Michigan (LSSCM) and the University of Michigan Law School. The program is a collaboration with legal help workplaces and housing counselors throughout Michigan, as well as the National Customer Law Center (NCLC).
ALWAYS call your local legal aid office totally free legal aid. NEVER pay a charge in exchange for assistance dealing with your lender. If you believe that you have actually been a victim of a foreclosure rescue rip-off, please submit a grievance with the Michigan Chief law officer's Office (click on link).
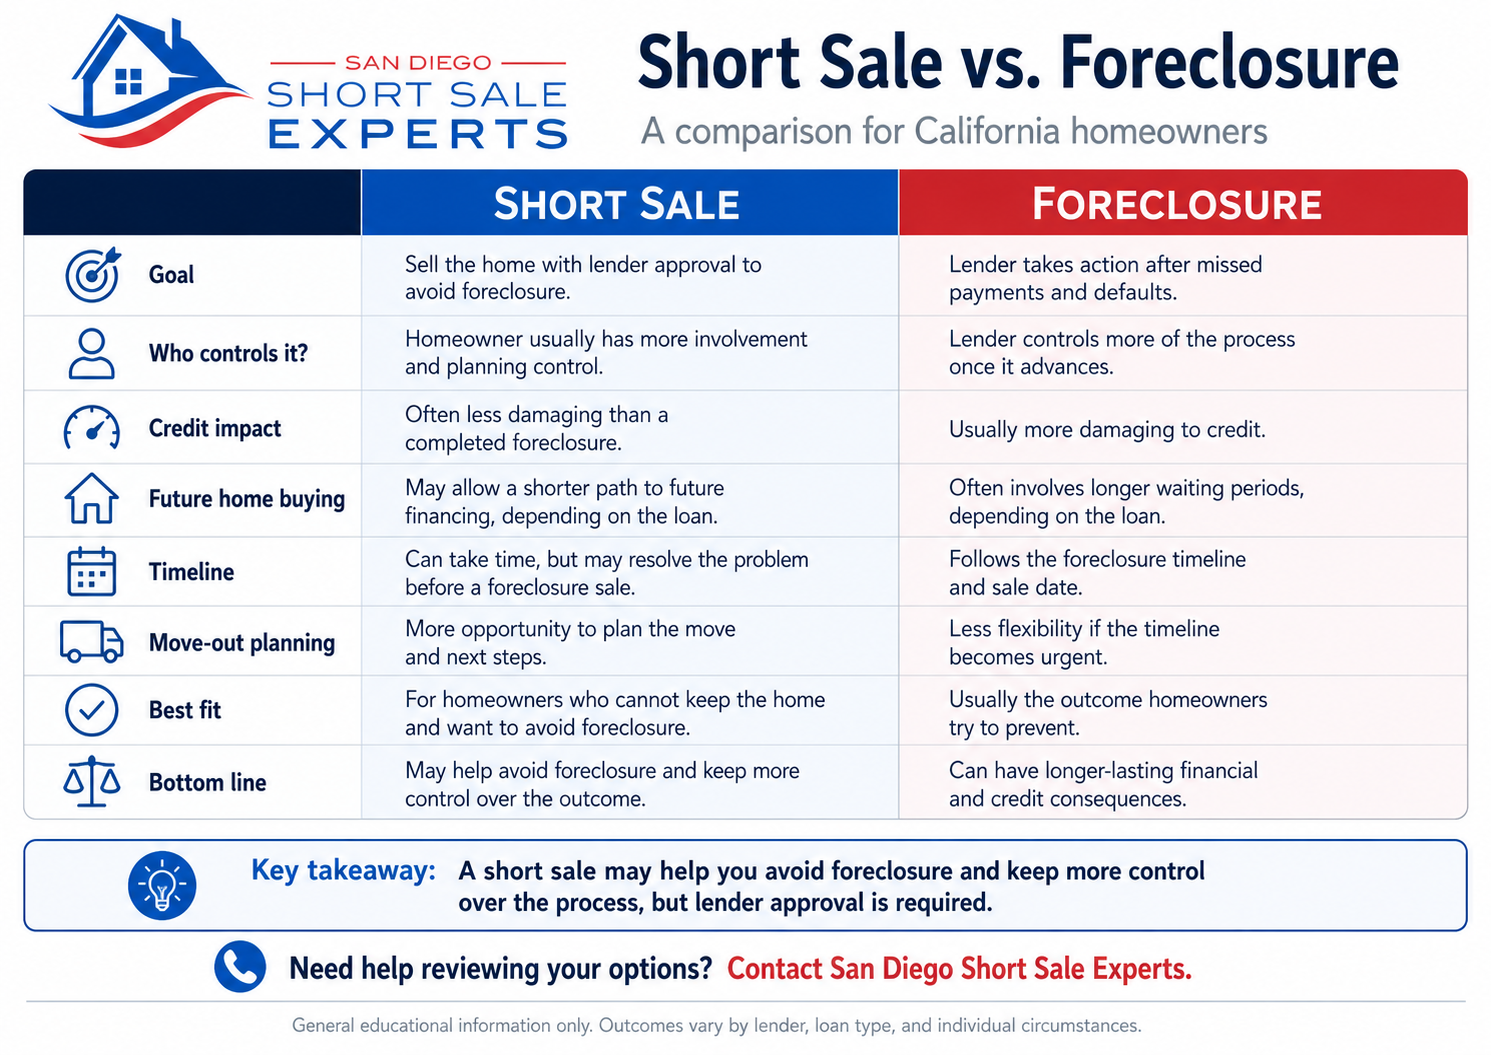
To prevent foreclosure in North Carolina, act within 120 days of your first missed payment. Your choices consist of: (1) reinstatement, paying all missed amounts plus fees, (2) loan forbearance, (3) loan adjustment, (4) short sale, (5) deed-in-lieu of foreclosure, or (6) selling your home for money before the foreclosure sale date.
Best Refinancing Strategies for Stopping Foreclosure
The NC foreclosure timeline, day by day Your 6 options at each stage What takes place if you do absolutely nothing When a cash sale makes good sense vs. other alternatives How to stop a foreclosure already in development frequently asked question (20 questions answered) Every year in North Carolina, roughly 6,000 to 9,000 homes go into the foreclosure process.
Foreclosure doesn't occur since individuals are careless. It occurs since life occurs. If you're one of those families today, the worst thing you can do is stop opening the mail and hope it disappears. The second worst thing is to presume you have actually already missed every window of chance.
We've closed handle as few as 2 week. If your foreclosure sale is thirty days away, we have time. If it's 2 week away, we might still have time. If it's tomorrow, we most likely don't, however call us anyhow. The one thing that makes every scenario worse is waiting.
North Carolina is a, which means most foreclosures take place without a claim, simply a short hearing before the Clerk of Superior Court. No foreclosure activity is permitted under federal law this early. The tone is still collection, not foreclosure.
This is still NOT the start of foreclosure. If you've applied for forbearance or adjustment and they have not responded, foreclosure generally can't start. Federal law typically avoids servicers from formally starting foreclosure up until you're more than 120 days past due.
You'll be served, face to face (10+ days before hearing), published on the home (20+ days before hearing), or through certified mail. Read this notice right away. It includes your hearing date. A short hearing is held before the Clerk of Superior Court. This is NOT a trial. The clerk only determines 4 things: the financial obligation is valid, you're in default, the servicer can foreclose, and the notice was proper.
Handling Debt with Strategic PlanningUnder N.C.G.S. 45-21.16, the clerk may delay if you have a reasonable ability to fix the default. If the clerk licenses foreclosure, you'll get a Notice of Foreclosure Sale consisting of: date of sale (at least 20 days out), time and place (usually courthouse steps), and minimum opening bid. The notice is also published in a regional newspaper for 2 consecutive weeks before the sale.
Preventing Default with Effective Loan Planning
The greatest bidder wins, typically the bank itself bids its exceptional loan balance. Under N.C.G.S. 45-21.27, for 10 days after the sale, ANYONE can come in and quote at least 5% greater than the winning quote.
This is the outright last legal window. From first missed out on payment to losing the home: usually 69 months.
Selling before foreclosure is submitted protects your credit more than offering after. Call us, call a housing therapist, call a bankruptcy attorney.

Latest Posts
Steps to Access 2026 Home Grants
Securing Federal Housing Programs in 2026

Essential Mortgage Help to Lower Monthly Payments